
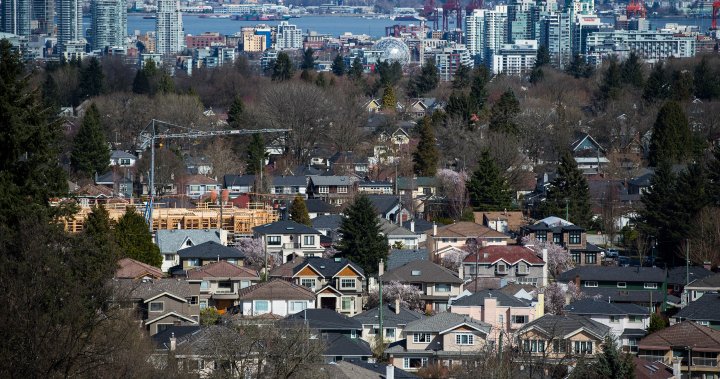

A barrier to entry in some of Canada’s most expensive housing markets just got lower thanks to new changes impacting the country’s mortgage landscape.
The ability to put less money down on an insured mortgage for a home worth more than $1 million will be a “game changer” for some buyers, real estate experts tell Global News.
But how much extra buying power Canadians get from a higher insured mortgage cap and wider availability of 30-year amortizations will vary from household to household and market to market, they warn.
The federal government’s previously announced changes aimed at making it easier for some Canadians to qualify for a mortgage will take effect on Sunday.
One such change will see all Canadians who are considered first-time homebuyers, as well as those buying new builds, able to take out an insured mortgage with an amortization period of 30 years, up from the typical 25 years.
Doing so lowers the bar to qualify for a mortgage and reduces the size of monthly payments, making the costs of carrying the home loan a bit more manageable, even as owners are likely to owe more over the lifetime of the mortgage.
The other major change is a hike to the price cap under which Canadians can take on insured mortgages, or mortgages with a high loan-to-value ratio. These mortgages allow Canadians to put less than 20 per cent down upfront on the purchase price of a home, reducing the savings barrier for buyers.
Under the new rules, Canadians can get an insured mortgage on anything priced at $1.5 million or lower, up from the previous cap of $1 million. That means that buyers will have an easier time saving for a home in some of Canada’s most expensive markets, such as Toronto and Vancouver, where property values routinely rise above $1 million.
Elliott Chun, a Realtor with The Partners Real Estate in Vancouver, tells Global News that the higher price cap is a “game changer” for his clients.
“There’s a feeling of optimism for the new year and being a busy spring market,” he says.
How will a higher insured mortgage cap affect these market?
Buyers will now be able to buy a home worth up to $1.5 million without having to put 20 per cent or more as a down payment on the home. Under the new rules, buyers will have to put down five per cent on the first $500,000 on the value of the home and 10 per cent for the remaining up to $1 million when taking out an insured mortgage.
For a home worth $1.5 million, that takes the minimum down payment requirement down to $125,000 from $300,000 previously.

Chun explains that in a market like Vancouver, $1 million will usually buy a household a new two-bedroom condominium in the downtown core with around 900 square feet of space.
Get weekly money news
Get expert insights, Q&A on markets, housing, inflation, and personal finance information delivered to you every Saturday.
But pushing that price up to $1.5 million could see buyers land twice the space with three or four bedrooms in a townhouse or semi-detached home, or buy in a different neighbourhood altogether.
“That extra $500,000 is a huge difference-maker in the marketplace,” Chun says.
“For buyers today, especially the couples or young families that are starting out … it’s really unlocking that door.”
Prospective homebuyers might find they’re able to access larger homes in entire markets that used to be prohibitively expensive, according to Phil Soper, CEO of Royal LePage.
According to the national brokerage’s home price index, there are 10 municipalities that will now be in play for buyers who were limited by the previous $1-million price cap.
Cities such as Victoria and Milton, Ont., where the median price for a detached home falls between $1 million and $1.5 million, are expected to see more activity in that price range as a result of the changes, Soper told Global News earlier this month.
“These are some of the most material changes that have been made in some time,” Soper said.
“So this is a big deal and it will add fuel to the recovery fire.”
What does that mean for prices?
The mortgage changes come on the heels of five consecutive interest rate cuts from the Bank of Canada this year. That’s also lowering the bar to qualify for would-be homebuyers, many of whom have been sidelined for much of the past two years.
The prospect of being able to afford a little bit more, both with the higher insured mortgage cap and the prospect of 30-year mortgages, has made the Vancouver real estate market busier than usual heading into the end of the year, Chun says.
He’s seeing activity heat up on properties priced between $1 million and $1.5 million as prospective buyers gear up for the new rules. He expects that will drive prices higher in the category.
For those with the buying power who can afford to put 20 per cent down, prices could even rise above the $1.5-million bar on some properties as buyers relying on the new insured mortgage cap are priced out above that amount.


“I’ve seen one set of clients experience this twice already, where they’ve gone over that $1.5 million,” he says.
Some experts who spoke to Global News when the changes were first announced in September argued that while the measures could improve affordability for some would-be buyers in the near term, lowering the barrier to entry would add to competition in the market, thereby stoking higher prices.
Chun recommended to Global News that buyers hoping to take advantage of the new mortgage rules not wait for the prospect of even lower rates from the Bank of Canada, as a flood of first-time buyers could all be hitting the market in the spring.
“I always like to remind my clients it’s a great opportunity to go out looking, get ahead of the crowd. No one wants to be in competition,” he says.
Do the mortgage math, expert advises
Victor Tran, Ratesdotca real estate and mortgage expert, tells Global News that while the new rules can be exciting for some buyers, the income levels needed to qualify for mortgages above a million dollars are still prohibitive.
“That’s a huge hurdle for most people,” he says.
For the average buyer, the change to a 30-year amortization will raise borrowing power by between three-to-five per cent, Tran says.
“It’s not a whole lot,” he says, adding that how much gain an individual gets from lengthier amortizations depends on credit ratings, liabilities and household income.
In terms of savings, Ratesdotca estimates that monthly payments would be roughly $48 lower for every $100,000 of mortgage debt taken on at an interest rate of five per cent. On a $700,000 mortgage under these conditions, that would mean paying roughly $286 less per month than under a typical 25-year amortization.
The fundamentals of securing a mortgage haven’t really changed, Tran says, and the higher insured mortgage cap really just speeds up the process of saving, rather than allowing buyers to qualify who would not have previously met the criteria.
“Now, it allows the first-time homebuyers out there that have been waiting to save up for the 20-per-cent down payment to enter the market earlier,” he says.
But for those Canadians who can afford to put down 20 per cent up front, Tran generally recommends doing so, even with the newly raised cap.
While insured mortgage rates tend to be lower on the face of them compared to uninsured products, the total costs tend to be higher thanks to insurance premiums. The Canada Mortgage and Housing Corp. confirmed earlier this year that it will raise its insurance premiums by an additional 20 basis points on mortgages it insures with a 30-year amortization, for instance.
“Yes, your interest rate is going to be a bit higher but you will be better off in the long run,” Tran says. “You’ve got to crunch the math.”
